Home Insurance for Bay Head’s Historic Shore Homes
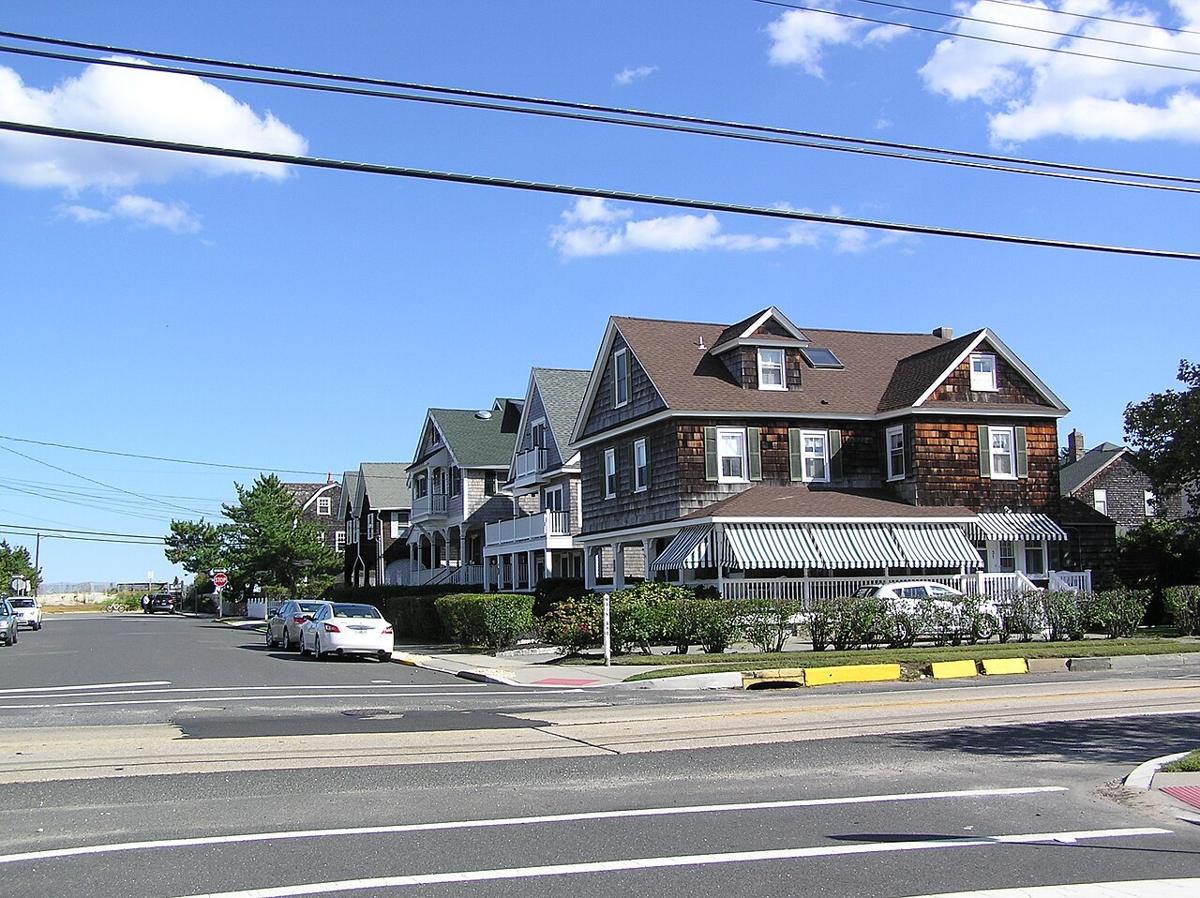
Many Bay Head homes are more than a century old: cedar shingle, wide porches, original millwork. Others are new and elevated. Both are expensive to rebuild, and both sit within a few blocks of the ocean or the bay.
Written and reviewed by Nate Feuerman, Stonebrook Insurance
Updated
To speak with an insurance advisor now, callCall an insurance advisor at (732) 905-4100Monday–Friday, 9 a.m.–5 p.m.
We’re closed right now. Leave your number and an advisor will call you back the next business morning.
Short answers
Is a historic home harder to insure?
Not with the right carrier. High-net-worth carriers can pay to rebuild with matching materials.
What’s a hurricane deductible?
A separate deductible for named-storm wind damage, usually 1% to 5% of the dwelling limit.
Is my summer home insured like a primary home?
No. It’s written as seasonal or secondary, with conditions about heat and water.
Does homeowners cover flood?
No. Flood needs a separate policy.
Bay Head homes, and what each needs.
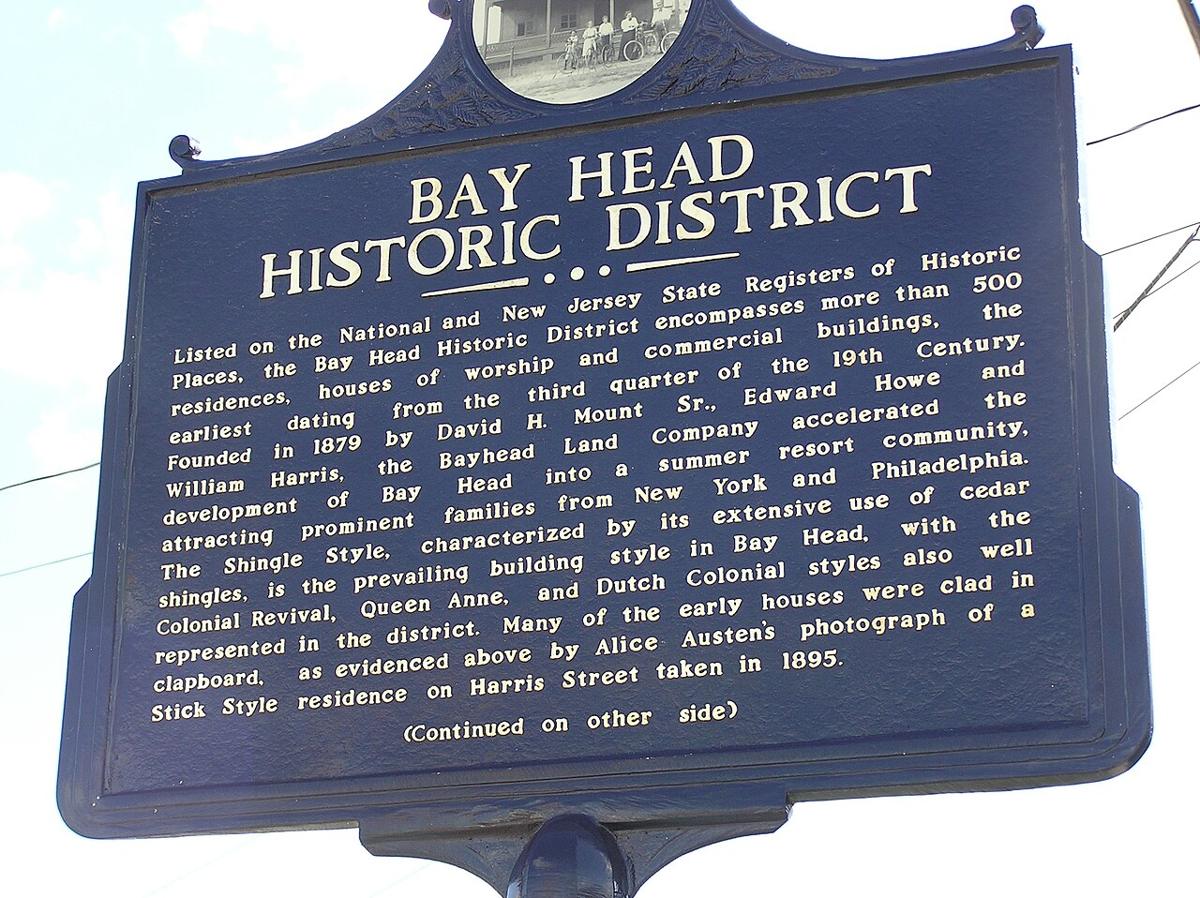
Historic Shingle-Style Cottages
Late-1800s and early-1900s homes in the historic district. Matching materials and older wiring and plumbing.
Oceanfront Homes
Behind the dunes and the buried seawall. Wind, surge and salt air.
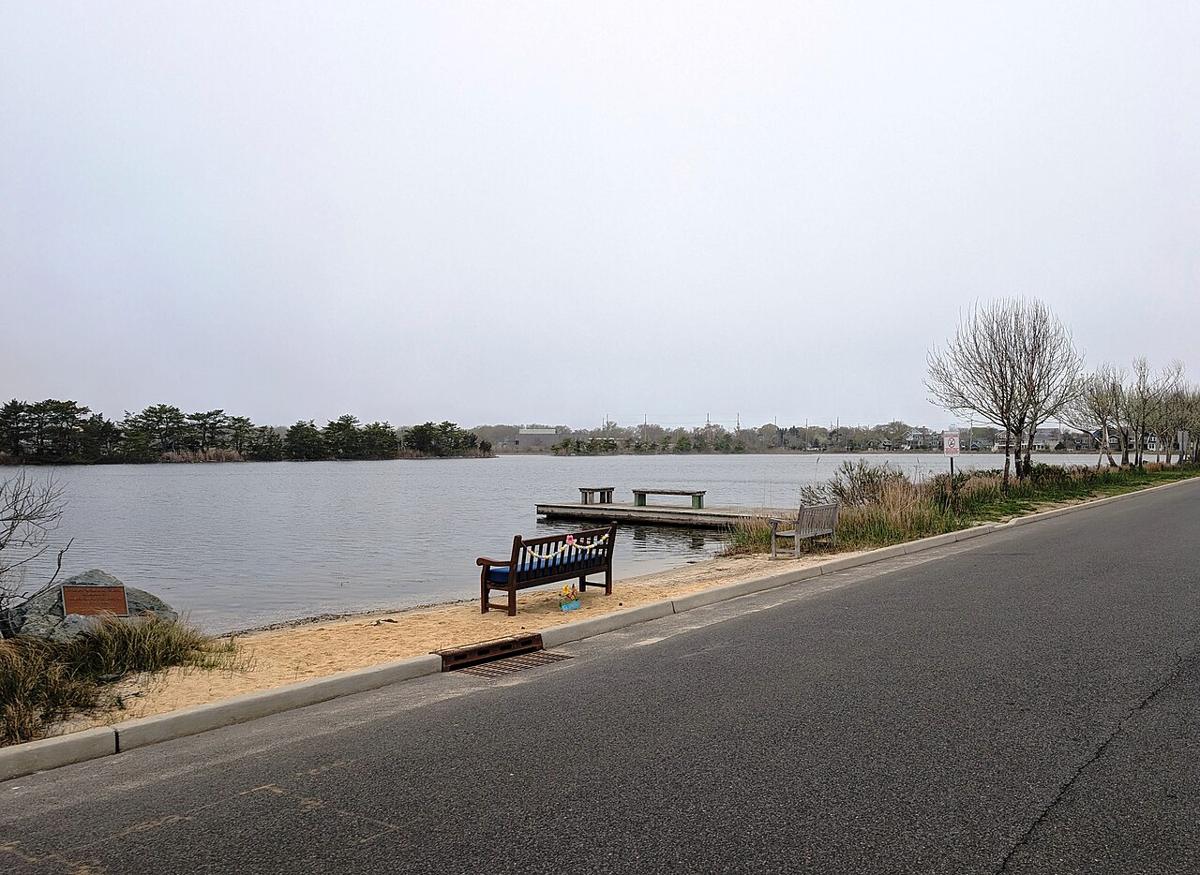
Bayfront and Lakefront Homes
On Barnegat Bay and Twilight Lake. Bay flooding comes more often.
New Elevated Homes
Rebuilt on pilings since Sandy. Rebuild cost and ground-level enclosures.
What causes claims in Bay Head homes.
Nor’easters and Hurricanes
Roofs, porches and windows; wind deductibles apply.
An Erosion Hot Spot
NJDEP lists this stretch as an erosion hot spot.
Empty in Winter
Frozen pipes in closed-up second homes.
Older Systems
Knob-and-tube wiring and old plumbing in some historic homes.
High Rebuild Cost
Craftsmanship and materials cost more to replace.
How we usually set up a Bay Head home policy.
| Coverage | Typical policy | What we usually recommend in Bay Head |
|---|---|---|
| Dwelling | A fixed limit | Guaranteed or extended replacement cost |
| Historic materials | Like kind and quality | Rebuild with matching materials |
| Wind deductible | Assigned | Chosen on purpose |
| Flood | Separate NFIP policy | NFIP plus excess, or private flood |
| Liability | $300,000 | $500,000 plus a large umbrella |
| Carrier | Standard | Private Client carriers |
A checklist for Bay Head owners.
- 01
Shut Off and Drain the Water
Or install an automatic shut-off valve.
- 02
Set the Heat and Add Alerts
Low-temperature and leak sensors.
- 03
Get the Wiring Checked
Especially in older homes.
- 04
Line Up a Caretaker
Someone who checks after storms.
- 05
Check Your Flood Limits
Large homes need more than the NFIP.
Own a home in Bay Head?
We’ll compare high-net-worth carriers and quote flood alongside.
What our clients say.
Five-star reviews from Stonebrook clients on Google.
“Great experience working with Stonebrook insurance company for our household insurance. They were responsive, professional, friendly, and never pushy. They took the time to find us the best rates and made the entire process smooth and stress-free. Highly recommended!”
“I've never gone with an Insurance brokerage and decided to give it a try and am so glad I did. I wasn't getting anywhere on my own with looking and comparing insurance for my home and automobiles and after trying several other agencies, Stonebrook Insurance Group became the clear choice! Ruth did an outstanding job finding the best insurance coverages and in the process, saved me a lot of money.”
“Nate is professional, knowledgeable and honest. I would totally recommend him for your home and auto. Best place in Howel.”
More for Bay Head homeowners.
What Bay Head homeowners ask us.
How much does home insurance cost in Bay Head?
It depends on rebuild cost, age, construction, elevation and distance to the water.
Will a carrier insure knob-and-tube wiring?
Some won’t. Updating it usually opens up better carriers.
Can you insure my boat too?
Yes, with agreed-value hull and named-storm haul-out coverage.
Neighbors: Mantoloking, Point Pleasant Beach, Point Pleasant, Brick, Lavallette.
Sources for this page
Figures come from the sources listed and are dated where the source gives a date. Coverage descriptions are general; your policy wording controls.
Let’s discuss how we can protect what you’ve built.
Take 30 seconds to take the first step towards better coverage.
Get a quote.
Tell us what you need and we’ll take it from there.