Home Insurance in Brick, NJ
Stonebrook is an independent insurance agency, protecting New Jersey homeowners since 1982 from our office in nearby Lakewood. Brick has bay and river lagoon neighborhoods on the mainland and a separate oceanfront section on the barrier island along Route 35. Here is what matters most for Brick homes. New to home insurance? Start with our home insurance guide.
Reviewed by Nate Feuerman, High Net Worth Insurance Producer at Stonebrook
Updated
Quick answers for Brick homeowners
Is Brick considered coastal for home insurance?
Yes, for most addresses. Brick has an oceanfront section on the barrier island and many lagoon neighborhoods on Barnegat Bay and the Metedeconk River, and even western Brick is only about 6 miles from the ocean.
Do I need flood insurance in Brick?
If you live near the bay, the river or on the island, you should strongly consider it.
What is a hurricane or wind deductible?
It is a separate, higher deductible for storm damage, usually a percentage of your dwelling limit instead of a flat dollar amount.
How much dwelling coverage should I have in Brick?
As of 2026, we like to see about $250 per square foot of living space as a starting point, and more for custom finishes.
From iron works township to a town on the water.
Brick Township was incorporated on February 15, 1850, from parts of Howell and Dover townships, the same day Ocean County was created. It was named for Joseph W. Brick, who revived the iron furnace at Bergen Iron Works on the Metedeconk River. That iron works village became Bricksburg and then Lakewood, which split off as its own township in the 1890s. Point Pleasant Beach, Bay Head, Mantoloking and Point Pleasant were also carved out of the original township.
For a century Brick was farms and small villages like Herbertsville, Burrsville, Laurelton and Osbornville. That changed when the Garden State Parkway opened in 1954. A housing boom followed from the 1950s through the 1980s, and Brick Township High School opened in 1958. In 1963, voters turned down a plan to rename the township “Laurelton.” In 2006, Brick was named “America’s Safest City” in the Morgan Quitno survey.
Today Brick covers 32.22 square miles, and about 20% of that is water. Most homes are on the mainland, including lagoon neighborhoods on Barnegat Bay and the Metedeconk River like Shore Acres, Cherry Quay, Baywood and Metedeconk. A separate section sits on the barrier island along Route 35, with three ocean beaches, Camp Osborn and part of Normandy Beach. Brick had 75,072 residents in 2010 and 73,620 in 2020, and the Census Bureau estimated 77,402 in 2025.
“Brick sits on the ocean, the bay and the Metedeconk River, and every one of them matters to your policy.”
Things to see in Brick.
A farmhouse museum, three ocean beaches, a bayfront park and a 1930s bungalow colony.
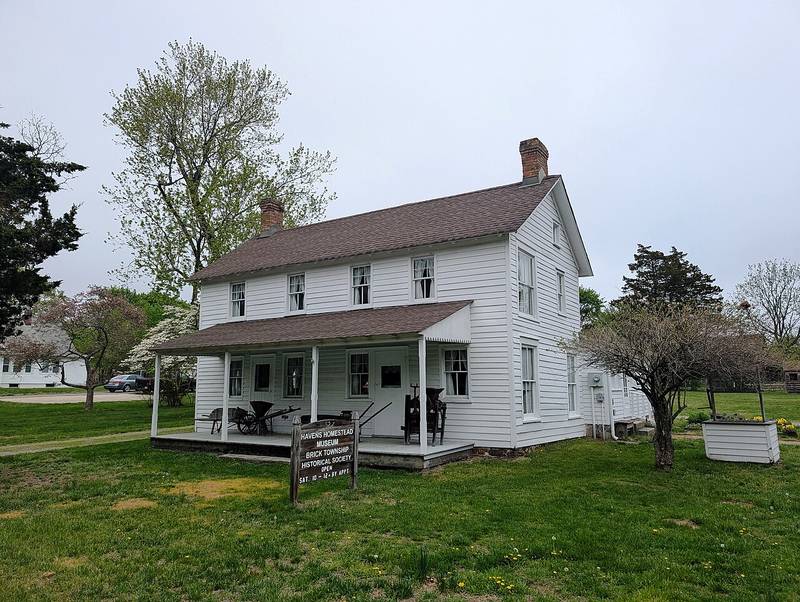
Havens Homestead Museum
Curtis Havens bought a one-room cabin and 52 acres here in 1827, and a five-room addition followed in 1846. The family kept it until 1993, then gave it to the Brick Township Historical Society. The c. 1790 Lizzie Herbert House was moved onto the grounds in 2002 as the museum store. At 521 Herbertsville Road; free, with Saturday tours in season.
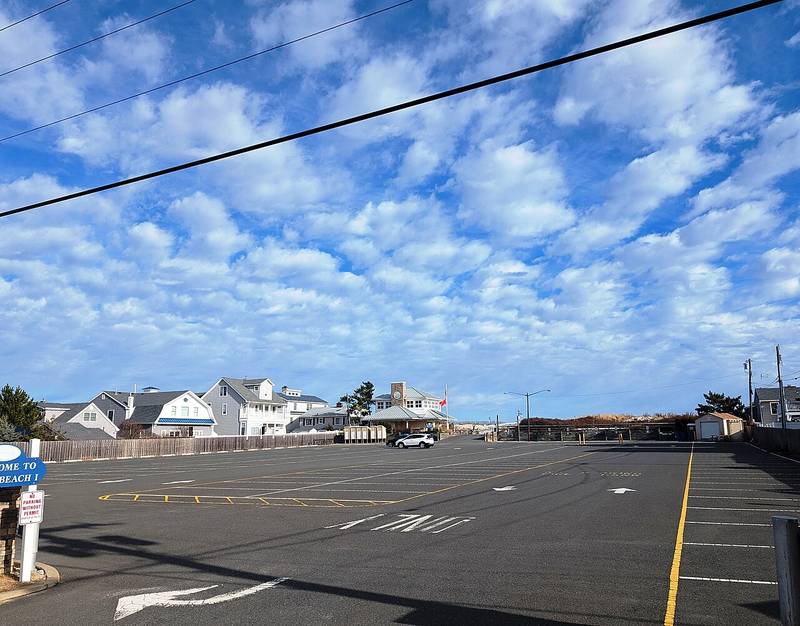
Brick Beach I
One of Brick’s three guarded ocean beaches on Route 35, with a large paved lot and beach buggy access. With a permit, buggies can drive from the Mantoloking line to Normandy Beach from October 1 to April 30.
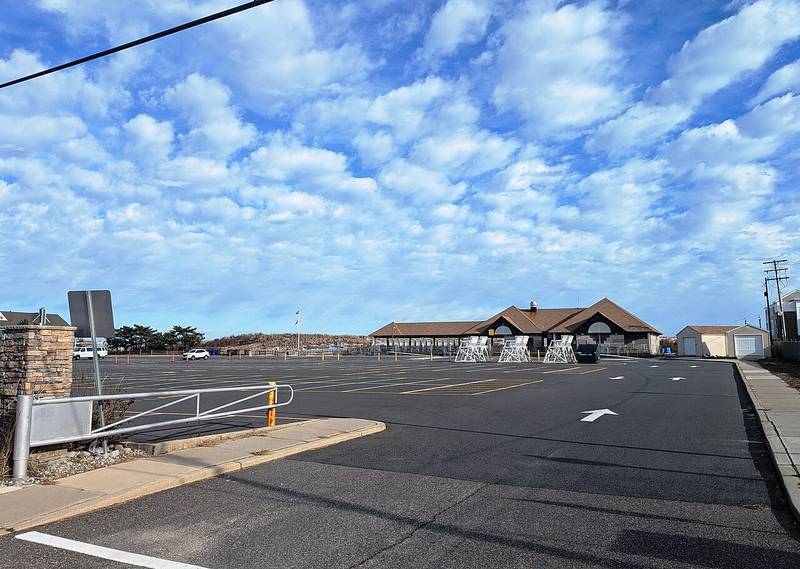
Brick Beach III
A guarded beach with a bathhouse and parking, across Route 35 from Bayside Park. The three beaches cover roughly half a mile of oceanfront and are popular for surfcasting for striped bass in the fall.
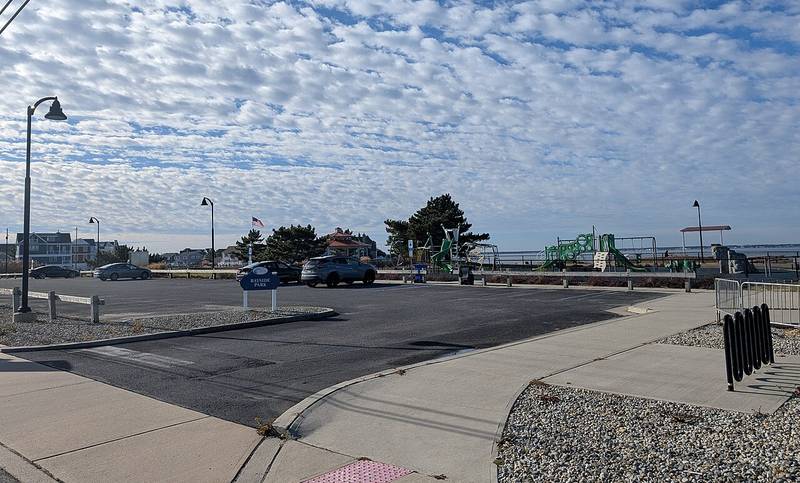
Bayside Park
A park on Barnegat Bay with a boardwalk, playground, gazebo and bait tables for fishing and crabbing. Sandy badly damaged it, and a $722,022 rebuild reopened it in October 2020.
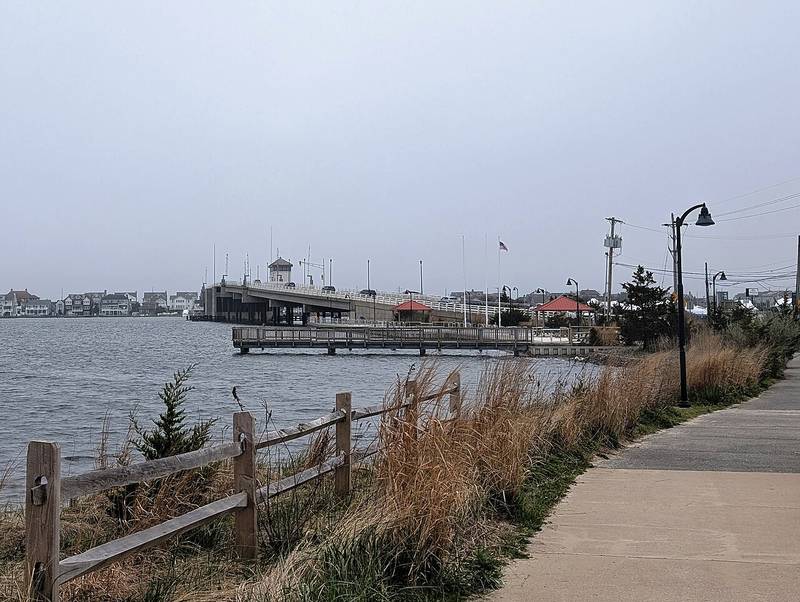
Mantoloking Bridge County Park
An Ocean County park on the Brick side of the Mantoloking Bridge, opened in 2012, with a 152-foot fishing pier built from a piece of the old span. The current bridge, a double-leaf drawbridge about 1,200 feet long, replaced it in 2006.
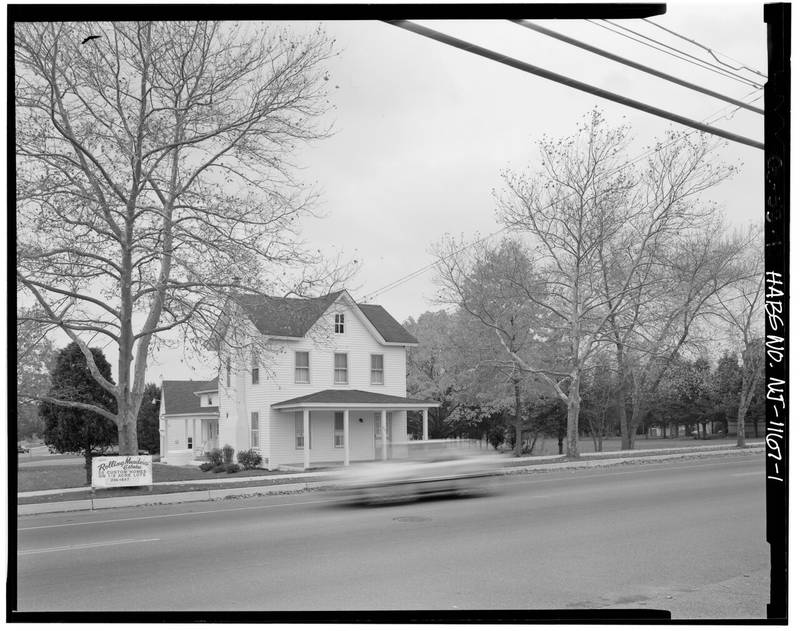
Herbertsville Road
Once a main route between Point Pleasant and Freehold. The Osborn farmhouse at 610 Herbertsville Road was built in 1850, with a Gothic-style addition in 1895, and is still in the same family. It is a private home, so view it from the road.
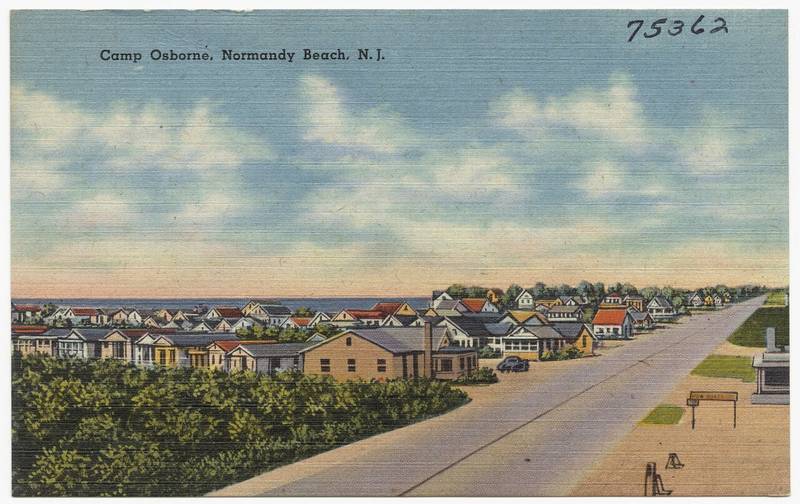
Camp Osborn
A bungalow colony between the ocean and the bay, shown here about 1930–1945. During Sandy, fires burned more than 70 homes there while the Mantoloking breach kept firefighters out.
Windward Beach Park
A bay beach on the Metedeconk River off Princeton Avenue. Brick’s July 4 Summerfest concert and fireworks are held here, and boaters watch from the river.
Brick Township Reservoir
80 acres with a 1.7-mile trail and fishing. It holds up to 1 billion gallons pumped from the Metedeconk River.
Ocean Ice Palace
A Brick ice rink since 1960, home of the Brick Hockey Club and the Brick Stars special needs hockey team.
Brick-specific insurance knowledge.
How close is the coast?
Brick is on the water. Its barrier-island section is oceanfront, and many mainland neighborhoods sit on lagoons off Barnegat Bay and the Metedeconk River. Even western neighborhoods near the Lakewood line are only about 4 to 5 miles from the bay and about 6 miles from the ocean. Many carriers price wind and hurricane risk by distance to the coast, so most Brick addresses are treated as coastal, and some carriers limit new policies close to the water. Expect a hurricane or wind deductible on many policies. It depends on the carrier and the address.
Hurricanes and Sandy
Sandy was no longer a hurricane when it came ashore near Brigantine on October 29, 2012, so New Jersey hurricane deductibles did not apply. It still did heavy damage in Brick. State data counted about 2,280 Brick homes with damage, most of it major or severe, and the mayor later said about 8,500 homes had water damage. On the barrier island, fires destroyed more than 70 homes in Camp Osborn. On the mainland, bay water flooded lagoon neighborhoods like Shore Acres and Cherry Quay, and the Shore Acres Yacht Club had to be torn down. By 2014, Brick had issued 396 demolition permits and 163 permits to raise homes. A 3.5-mile steel seawall was later built under the dunes through Mantoloking and Brick’s Normandy Beach section.
“More than 70 homes burned at Camp Osborn during Sandy.”
Wind, nor’easters and falling trees
Most years, the claims here are wind and falling trees. On July 22, 2019, a thunderstorm knocked out power to more than 28,000 of Brick’s roughly 35,800 electric customers, and trees fell on homes. After Tropical Storm Isaias on August 4, 2020, nearly 11,000 customers were still without power the next morning. Nor’easters bring wind and high tides together: a week after Sandy, Brick ordered waterfront neighborhoods evacuated ahead of a November 2012 nor’easter.
Fire
Wildfire is a real risk on Brick’s wooded western side. On March 14, 2021, a fire set in Lakewood near Cedar Bridge Avenue burned about 170 acres, jumped the Garden State Parkway into Brick and forced the evacuation of several hundred homes. It destroyed a commercial building and damaged sheds. If your home backs onto woods, keep brush, leaves and dead branches cleared.
Rain and flooding
In Brick, flooding comes mostly from the bay and tides. Lagoon neighborhoods on Barnegat Bay and the Metedeconk River flood when high tides and storm surge top the bulkheads. On December 27, 2012, a midday high tide spilled over bulkheads in Shore Acres and Cherry Quay. Heavy rain can also back up drains and sump pumps inland. Brick has mapped flood hazard areas along the bay, the river and the island, and it has been in the National Flood Insurance Program since 1972. We recommend at least $25,000 of water backup coverage. Flood is a separate policy, so ask about it.
Home values and your dwelling limit
The U.S. Census Bureau puts the median value of an owner-occupied home in Brick at $410,600 (2020–2024 American Community Survey), and about 82% of homes are owner-occupied. Waterfront and barrier-island homes, many rebuilt and raised after Sandy, can be worth much more. Rebuild cost is a different number from market value, so check your limit against our 2026 guideline of about $250 per square foot.
Check your Brick home in two minutes.
Three quick checks for any Brick home insurance policy.
1. Dwelling coverage guideline
Our 2026 starting point is about $250 per square foot. Custom finishes cost more.
2. Hurricane deductible
A percentage deductible applies to hurricane or wind damage, not to every claim.
3. Your flood zone
Look up your address on FEMA’s official flood map. Zones starting with A or V are high risk, and a lender will usually require flood insurance there. Homes outside those zones can still flood.
Check my flood zone on FEMA’s mapNot sure how to read it? Send us your address and we’ll tell you what it means for your Brick home.
What Brick homeowners should ask about.
- 01
Waterfront and lagoon homes
Bulkheads, docks and lagoon frontage change how carriers see your home. Expect questions about elevation and distance to the water, and a hurricane or wind deductible. Ask about a separate flood policy, even if your lender does not require one.
- 02
Raised and rebuilt homes
Many Brick homes were raised or rebuilt after Sandy. A higher first floor can lower flood premiums, so get an elevation certificate. New construction costs more to rebuild, so start at about $250 per square foot and add for custom finishes.
- 03
Basement apartments, ADUs and rentals
A basement apartment or a summer rental on the island can make your home a rental property to the carrier. You may need a landlord or dwelling fire policy (DP-3). Disclose the unit, or a claim can run into trouble.
- 04
Water backup and sump pumps
Heavy rain and power outages can stop a sump pump and back up drains. Keep at least $25,000 of water backup. It is not flood coverage, which is a separate policy.
- 05
Hosting, pools and boats
Pools, docks, boats and big gatherings raise liability risk. Ask about higher liability limits and an umbrella policy, and tell us about pools, trampolines, dogs and temporary structures like a sukkah.
- 06
Jewelry, silver and Judaica
Standard policies often cap jewelry and silver theft at a few thousand dollars. Schedule jewelry, watches, silver Judaica and other valuables item by item with appraised values.
- 07
Vacation homes
Own a second home in Florida or elsewhere? We place home coverage in all 50 states.
“A 2% hurricane deductible on a $500,000 home is $10,000 out of pocket.”
Stonebrook is an independent insurance agency.
We don’t work for one insurance company.
We work with more than 25 carriers and compare coverage for your Brick home. If another carrier fits your home better, we can place it there. Protecting New Jersey homes since 1982.
What clients say about Stonebrook.
“Super smooth getting my home reinsured through them. I emailed them my policy and they sent me a back a better one. Great experience working them”
“This is the best insurance broker in Lakewood and surrounding areas they are honest and not pushy at all it was a pleasure talking to Nate they have the best rates that I have found thanks! Definitely recommend as top 5!”
“Working with Ruth from Stonebrook was a pleasure she was knowledgeable and super helpful on giving me a auto insurance quote for my cars in Lakewood”
Brick home insurance questions, answered.
What is an independent insurance agency?
An independent agency works with many insurance companies instead of one. Stonebrook is independent and compares more than 25 carriers for your home.
Is Brick considered coastal for home insurance?
Yes, for most addresses. Brick has an oceanfront section on the barrier island and many lagoon neighborhoods on Barnegat Bay and the Metedeconk River, and even western Brick is only about 6 miles from the ocean. How a carrier treats your home depends on the carrier and the address.
Do I need flood insurance in Brick?
If you live near the bay, the river or on the island, you should strongly consider it. Standard homeowners policies exclude flood, and Sandy and tidal flooding have flooded homes in Brick lagoon neighborhoods. If you have a federally backed mortgage in a high-risk flood zone, your lender will require it.
How do I check if my address is in a flood zone?
Search your address on FEMA’s Flood Map Service Center at msc.fema.gov. It shows your flood zone on the current map. Homes outside a mapped zone can still flood, so ask us either way.
How much does home insurance cost in Brick?
It depends on your home, your carrier and your distance from the water. For reference, NerdWallet put New Jersey’s average at $2,030 a year in 2026 for a sample policy with $600,000 of dwelling coverage. Waterfront homes often cost more. We compare more than 25 carriers to find the right price for your home.
What is a hurricane or wind deductible?
It is a separate, higher deductible for storm damage, usually a percentage of your dwelling limit instead of a flat dollar amount. A 2% deductible on a $500,000 home is $10,000. Check what triggers yours and how high it is.
Does my homeowners policy cover a neighbor’s tree falling on my house?
Usually, yes. Your own policy typically pays to repair your house, minus your deductible, no matter whose yard the tree grew in. The neighbor is generally responsible only if they were negligent, for example if they ignored a tree they knew was dead.
Is my sukkah covered?
Often, but check your policy. A sukkah is usually treated as an other structure or as personal property, and wind damage to it may be covered. Liability coverage applies to guests who get hurt, so make sure your limits are high enough.
Do I need to tell my insurance company about a basement apartment?
Yes. A separate unit that someone lives in can make your home a multifamily dwelling to the carrier. You may need a landlord or dwelling fire policy (DP-3), and tenants may need renters insurance. Disclose the unit to avoid problems at claim time.
How much dwelling coverage should I have in Brick?
As of 2026, we like to see about $250 per square foot of living space as a starting point, and more for custom finishes.
Can Stonebrook insure a vacation home outside New Jersey?
Yes. We place home coverage in all 50 states through our carriers and partners.
Does raising my Brick home after Sandy lower my insurance?
It can lower your flood insurance. Flood premiums depend heavily on how high your lowest floor sits, so get an elevation certificate and send it to us. Your homeowners premium depends more on rebuild cost, which is often higher for a raised or rebuilt home.
Nearby towns we cover.
Every town has its own risks. See what matters for homes near Brick.
Get a free second opinion on your Brick policy.
- Upload your declarations page. It’s the summary page of your policy, usually 1–3 pages. A photo works.
- We check it against your Brick home. Dwelling limit, water backup, wind deductible, flood, liability and valuables.
- You get a plain answer. What’s fine, what’s missing, and whether one of our 25+ carriers can do better. No pressure.
Send us your policy.
We’ll look it over and get back to you with a plain answer.
Let’s make sure your Brick home is covered correctly.
Take 30 seconds to take the first step towards better coverage.
Get a quote.
Tell us what you need and we’ll take it from there.
Sources (27)
Facts on this page come from these public sources. Figures are as of the dates shown in the text.
- en.wikipedia.org · Brick Township, New Jersey
- lakewoodnj.gov · history
- census.gov · PST045223
- theclio.com · entry
- shorebeat.com · centuries of brick history are nestled in the middle of modern neighborhoods
- thefisherman.com · brick beaches
- patch.com · brick township three family friendly ocean beaches
- shorebeat.com · redesigned brick park to reopen oct 5 officials announce
- patch.com · county s mantoloking bridge park officially open
- shorebeat.com · ocean county to make improvements to mantoloking bridge fishing pier
- constructionequipmentguide.com · bridge over barnegat rises to new heights
- shorebeat.com · brick summerfest begins july 4 with concert fireworks shuttle buses will be runn
- patch.com · sandy by the numbers 2 280 homes damaged in brick map8a8a0d5f6b
- whyy.org · shore community changed utterly by sandy
- shorebeat.com · two years later a forever changed brick township
- shorebeat.com · rare video shows up close view of brick neighborhood burning during sandy
- patch.com · bittersweet demolition project begins at camp osborn
- inquirer.com · 20141208 Seawall project nearing completion on Jersey Shore
- patch.com · tidal flooding hits some neighborhoods breaches repor64a7c5fce2
- cbsnews.com · mandatory evacuation ordered by 6 p m for low lying parts of brick township
- patch.com · storm brings down trees wires 28k without power brick
- patch.com · nearly 11k still without power brick after isaias
- shorebeat.com · prosecutor brick lakewood brush fire was intentionally set
- cbsnews.com · garden state parkway route 70 brush fire
- webarchive.library.unt.edu · cis
- nerdwallet.com · homeowners insurance nj
- msc.fema.gov
Photo credits
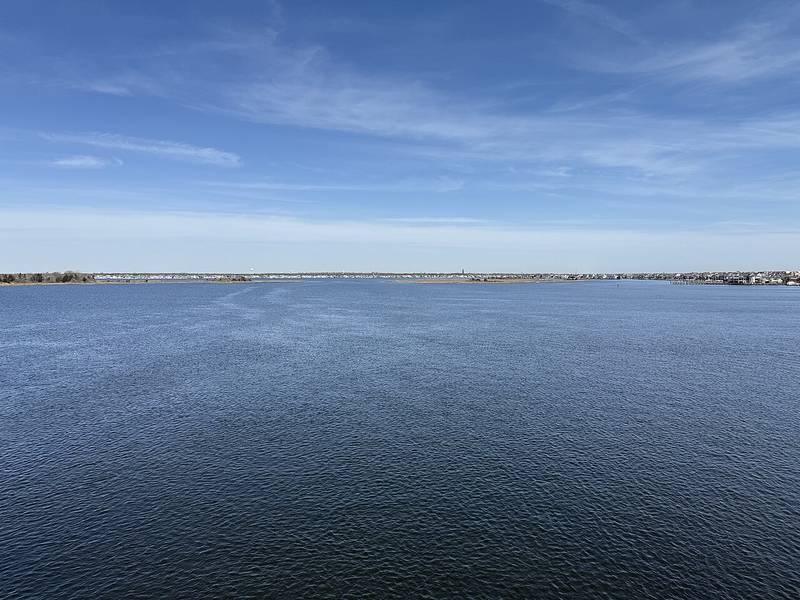
- “View north up Barnegat Bay from the Mantoloking Bridge” by Famartin, CC BY-SA 4.0. Source: Wikimedia Commons
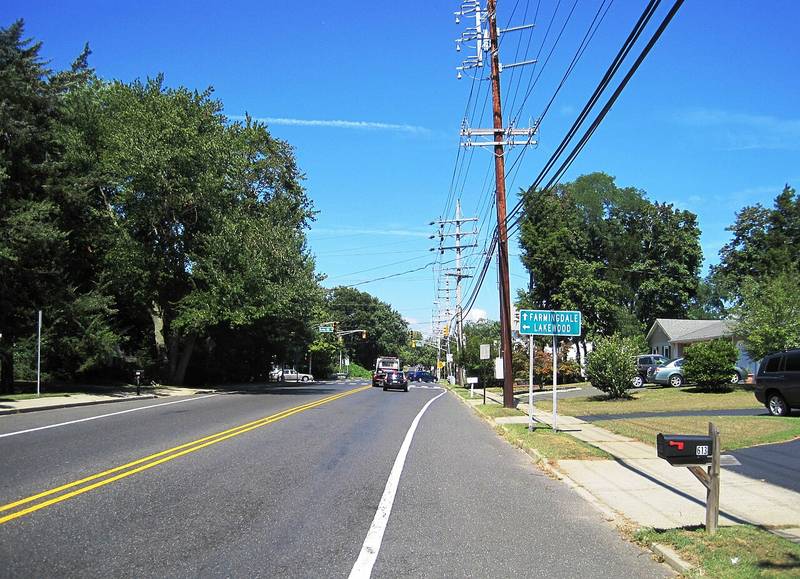
- “Herbertsville, NJ” by Mr. Matté, CC BY 4.0. Source: Wikimedia Commons
- “Havens Homestead Museum, Brick Township, NJ, April 2026” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Brick Beach I, NJ, Dec. 2024” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Brick Beach III, NJ beach house, Dec. 2024” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Bayside Park, Brick Township, NJ, Dec. 2024” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Mantoloking Bridge from west, April 2026” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Perspective view looking southwest - Osborn Farmhouse, 610 Herbertsville Road, Herbertsville, Ocean County, NJ” by Historic American Buildings Survey, Public domain. Source: Wikimedia Commons
- “Camp Osborne, Normandy Beach, N. J. (8489495610)” by Boston Public Library, CC BY 2.0. Source: Wikimedia Commons


