Home Insurance for Alpine Estates
An Alpine home is often a compound: main house, guest house, pool house, staff quarters, a long gated drive and systems that run all of it. The most important number is what it would really cost to rebuild every piece, and most standard policies get it wrong.
Written and reviewed by Nate Feuerman, Stonebrook Insurance
Updated
To speak with an insurance advisor now, callCall an insurance advisor at (732) 905-4100Monday–Friday, 9 a.m.–5 p.m.
We’re closed right now. Leave your number and an advisor will call you back the next business morning.
Short answers
What’s the biggest claim risk in an Alpine home?
Water damage. In large homes, a burst pipe or failed fitting can run for hours before anyone notices.
What is guaranteed replacement cost?
Coverage that rebuilds the home even if it costs more than the policy limit. Many high-net-worth carriers offer it.
Do carriers require security systems?
Most high-net-worth carriers expect central-station burglar and fire alarms, and many credit gates, cameras and leak detection.
Should art and wine be on the homeowners policy?
They should be scheduled at appraised value, on the homeowners policy or a separate collections policy.
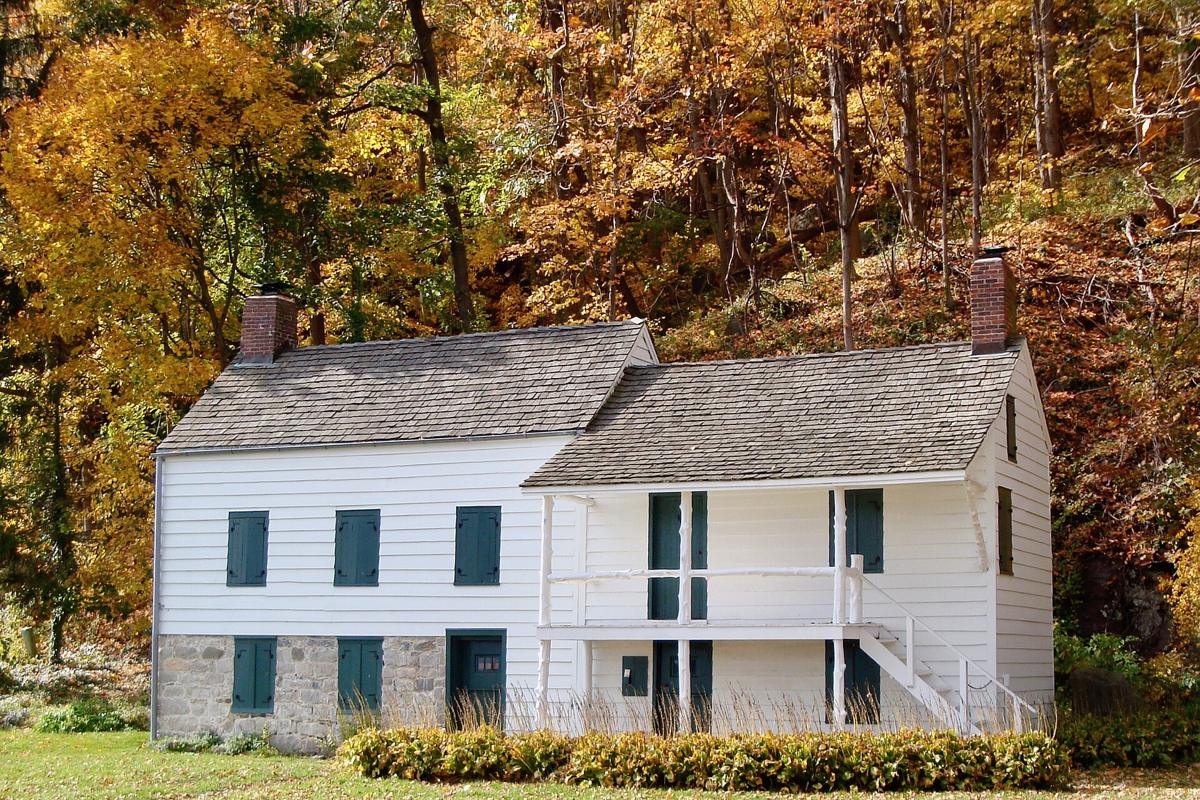
Alpine homes, and what each needs from a policy.
New Estates
Large new homes with stone, imported finishes, smart-home systems, wine rooms and home theaters. Rebuild cost and water damage are the key issues.
Rio Vista
The neighborhood on the former Rionda estate in the south end, subdivided in the 1980s into large homes on generous lots.
Older Alpine Homes
Mid-century and older homes on wooded lots, many being expanded or replaced. Renovations need builder’s risk coverage.
Compounds
Guest houses, pool houses, garages and staff quarters. Each structure needs a limit that fits it.
What causes claims in Alpine homes.
Burst Pipes and Leaks
The most common large claim in big homes. Automatic water shut-off valves and leak sensors prevent most of them, and many carriers credit them.
Wooded Acreage
Mature trees on large lots come down on roofs, drives and cars in nor’easters and summer storms.
Outages
Long outages strand sump pumps, freeze pipes and shut down systems. Whole-house generators matter.
Theft and Privacy
Gates, cameras and monitored alarms are standard, and carriers ask.
Staff, Guests and Pools
Household staff, frequent guests, pools and drivers all add liability. Umbrellas of $5–25 million are common.
Construction
A major renovation can void or limit coverage unless it’s disclosed and properly insured.
How we usually set up an Alpine home program.
Placed through Stonebrook Private Client.
| Coverage | Standard policy | What we usually recommend in Alpine |
|---|---|---|
| Dwelling | A fixed limit | Guaranteed or extended replacement cost, based on a professional appraisal |
| Other structures | 10% of dwelling | Each guest house, pool house and garage valued separately |
| Contents | 50% of dwelling, actual cash value | Replacement cost, often 70% or more of dwelling |
| Collections | Low sublimits | Art, jewelry, wine and watches scheduled at appraised value |
| Water backup | Excluded or low | High limits, plus leak detection |
| Umbrella | $1 million | $5–25 million, with excess uninsured motorist |
A checklist for Alpine homeowners.
- 01
Get a Professional Appraisal
High-net-worth carriers often provide one free. It sets the rebuild cost.
- 02
Install Water Shut-Off Valves
The single best way to prevent a large claim.
- 03
List Every Structure
Guest house, pool house, garages, gatehouse and staff quarters.
- 04
Update Collection Appraisals
Art, jewelry and wine values change.
- 05
Tell Us About Renovations
Before work starts.
- 06
Check Workers’ Comp for Staff
Housekeepers, nannies, drivers and landscapers.
Own an Alpine home?
We’ll compare high-net-worth carriers and review your home, collections, staff and umbrella together.
What our clients say.
Five-star reviews from Stonebrook clients on Google.
“Nate and the whole Stonebrook team were great! From the beginning, down to the last minute. It was a breeze working with them. Had great insurance programs for my home, and kept me informed of all my options. They really came through, even on a last minute closing. 10/10 Highly recommended”
“Super quick and easy to deal with. Saved a few hundred dollars on my homeowner's policy, with almost no effort on my end.”
“Stonebrook is the best insurance broker i have worked with. They researched to find me the best policy for the best price while still providing advice on limits my policy should be at. Excellent service!”
More for Alpine families.
What Alpine families ask us.
How much does home insurance cost in Alpine?
It depends on the appraised rebuild cost, protective devices, claims history and the carrier. High-net-worth carriers often offer broader coverage at competitive prices for homes this size.
Do I need flood insurance in Alpine?
Most Alpine homes are high above the river, outside flood zones. Water damage from inside the house is the more common risk.
Is a renovation covered?
Only if it’s disclosed. Large projects usually need a builder’s risk policy.
Are household staff covered by my homeowners policy?
Not for their injuries. Workers’ compensation for household employees is usually needed.
Can you insure my art and wine?
Yes, scheduled at appraised value, on the homeowners policy or a separate collections policy.
Neighbors: Tenafly.
Sources for this page
Figures come from the sources listed and are dated where the source gives a date. Coverage descriptions are general; your policy wording controls.
Let’s discuss how we can protect what you’ve built.
Take 30 seconds to take the first step towards better coverage.
Get a quote.
Tell us what you need and we’ll take it from there.